Executive Summary
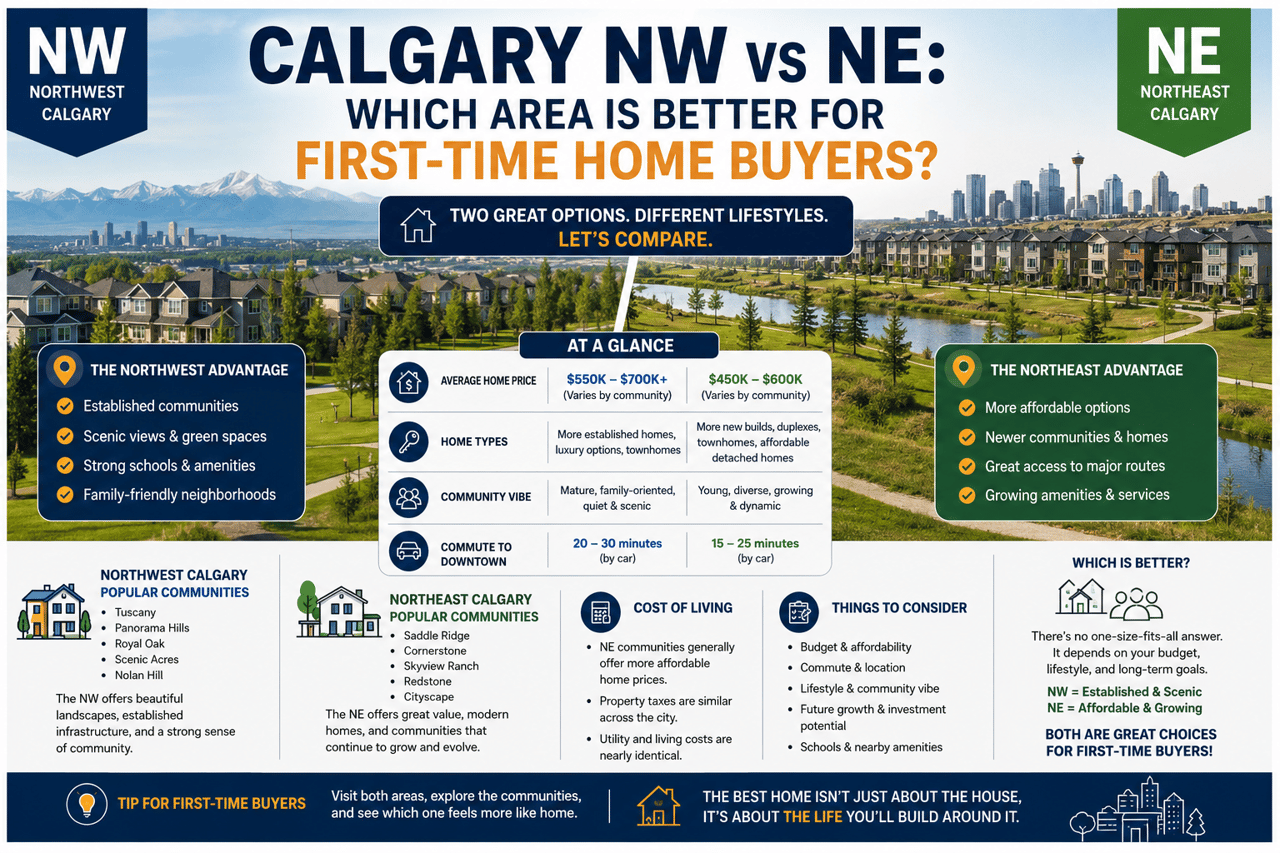
For most first-time home buyers in Calgary, the North East usually wins on entry price, while the North West wins on price stability, neighbourhood prestige, and detached-home resale strength. April 2026 CREB district benchmarks show a large gap at the detached level: about $795,500 in the North West versus $565,100 in the North East. The gap narrows at the apartment and row levels, but it still matters to down payment requirements, mortgage qualification, and monthly carrying costs. In practical terms, buyers focused on getting into the market at the lowest cash entry point will often find better options in NE communities such as Saddle Ridge, Skyview Ranch, Redstone, and Cornerstone, while buyers prioritizing long-run resale quality and a more established NW buyer pool often lean toward NW communities or the northern arc communities they are also cross-shopping. (CREB April 2026; City of Calgary community profiles).
A key local nuance is that Panorama Hills and Coventry Hills are formally treated in City/CREB materials as part of Calgary’s northern arc rather than the strict CREB North West district. However, first-time buyers routinely compare them against both NW and NE options because they compete in the same broad suburban, family-oriented price bands. In that sense, Panorama Hills and Coventry Hills function as a middle-ground comparison set: usually more expensive than the most affordable NE choices, but often cheaper than many true NW entry points.
Abstract
This post evaluates whether Calgary NW or NE is the better choice for first-time home buyers by comparing district-level benchmark pricing, mortgage qualification rules, estimated ownership costs, and representative neighbourhood examples. The analysis emphasizes first-time buyer constraints under 2026 Canadian financing rules, including minimum down payments, insured mortgage availability up to $1.5 million, 30-year amortizations for first-time buyers, and the federal stress test. (CMHC; Department of Finance Canada; OSFI; FCAC).
The evidence suggests that affordability is not determined by sticker price alone. Buyers must evaluate actual cash needed at closing, condo versus detached risk, and the monthly ownership burden that follows possession. The result is not a one-size-fits-all answer: NE is usually better for first-time access, while NW is often better for buyers who can stretch their budget and want the strongest positioning for future resale.
Methodology
This comparison relies primarily on the Calgary Real Estate Board’s April 2026 monthly district benchmarks and citywide days-on-market figures, the City of Calgary’s 2026 residential property tax rate, CMHC mortgage insurance rules, OSFI’s current mortgage qualifying rate guidance, and Statistics Canada’s 2021 Census affordability context for the Calgary CMA. Because neighbourhood-level days on market are not consistently published in the same way as district data, broader Calgary property-type averages are used where needed. This is consistent with the instruction to use broader Calgary averages when neighbourhood-level data is not available.
Illustrative monthly payment examples assume a 4.69% five-year fixed mortgage rate purely for budgeting demonstration. That rate is an analytical assumption, not a live lender quote. Where condo-fee ranges are shown, they are budgeting ranges drawn from current Calgary market guidance and typical observed listing patterns; actual condo fees vary materially by unit size, age, amenity package, reserve-fund health, and what utilities are included.
Market Context
Calgary entered May 2026 in a more balanced resale market than the tight conditions seen in prior years. CREB’s daily and monthly summaries show lower year-over-year sales, materially higher active listings than in 2024, and a citywide benchmark around $568,800 in April 2026. That balance helps first-time buyers because it increases selection and reduces some of the urgency that defined the previous cycle, especially in apartments and row housing.
Affordability remains the central constraint. Statistics Canada reports Calgary CMA median after-tax household income at about $87,000 in 2020 and median monthly shelter costs for owned dwellings at about $1,720, with 5.6% of households in core housing need. Those figures matter because they show why many first-time buyers are pushed toward condos and townhomes rather than detached homes, even in a softer market.
At the district level, April 2026 CREB benchmark prices show the broad hierarchy clearly. Detached benchmarks were about $795,500 in the North West, $645,400 in the North, and $565,100 in the North East. Row benchmarks were about $427,700 in the North West, $386,200 in the North, and $349,000 in the North East. Apartment benchmarks were about $294,600 in the North West, $300,300 in the North, and $261,500 in the North East. In other words, NE has the lowest entry pricing, while the strict NW district carries the strongest premium.
Data Analysis
Canadian mortgage rules in 2026 continue to shape what “better” really means for first-time buyers. CMHC’s insured minimum down payment remains 5% on the first $500,000 and 10% on the portion above $500,000, insured mortgages are generally unavailable at $1.5 million and above, and CMHC confirms that 30-year amortizations are available to first-time buyers and buyers of new builds under eligible insured structures. OSFI’s published qualifying rate for uninsured mortgages remains the greater of the contract rate plus 2% or 5.25%, and FCAC notes that banks generally apply the same stress-test logic when qualifying borrowers.
That means first-time buyers do not simply need enough income for the real payment; they need enough income for the stressed payment. For an illustrative $525,000 purchase with the minimum $27,500 down payment, the insured mortgage balance after the premium would be about $517,400. At an assumed 4.69% rate over 30 years, the actual payment is about $2,680 per month, but the qualification test at 6.69% pushes the underwriting payment to roughly $3,335 before taxes, heat, and condo fees. A smaller $320,000 purchase with 5% down produces an insured balance of roughly $316,160, an actual payment near $1,638 per month, and a stress-tested payment of about $2,038. That gap is why NE often works better for first-time buyers even when the monthly lifestyle difference between areas appears modest. (CMHC; OSFI; FCAC; illustrative calculations).
CMHC also advises that housing costs should generally stay under 32% of gross income, counting mortgage principal and interest, property taxes, heating, and half of condo fees in the GDS framework. On that basis, a buyer carrying an all-in cost around $2,400 per month is living in a very different affordability universe from a buyer carrying $3,500 or more. The district comparison therefore matters most at the row and detached level, where the price gaps are widest.
The table below uses CREB April 2026 benchmarks, the City of Calgary’s 2026 residential tax rate of 0.0066499, citywide April 2026 days on market by property type, and budgeting ranges for condo fees commonly observed in Calgary’s current market. Where district-specific DOM is unavailable, the citywide property-type DOM average is used.
Two additional observations matter. First, true NW detached buying is usually not a first-time buyer play unless household income and savings are already well above median. A near-$800,000 benchmark price requires a materially larger down payment and a much bigger qualification buffer than an NE alternative. Second, Panorama Hills and Coventry Hills often act as compromise markets for buyers who want suburban product and family-oriented community form without paying the full NW premium. They are not the cheapest path into ownership, but they can be an effective middle option for buyers whose budget is too strong for entry-level NE condos but not strong enough for many NW detached homes.
Condo versus detached comparisons also cut differently by area. Condos lower the entry barrier, but they add fee risk and assessment risk. CREB notes that condos require monthly fees that can rise over time and can also face special assessments, while detached homes avoid condo governance risk but shift all maintenance and repair responsibility to the owner. For first-time buyers, that means NE condo affordability can look strongest on paper, but poorly managed condo corporations can erase part of that advantage.
Practical Recommendations
If your maximum comfortable budget is below about $350,000, NE usually provides the strongest first-home entry point because apartment benchmarks are lower and the gap in required cash is meaningful after the stress test. If your budget is in the roughly $375,000-$475,000 range, the most useful comparison is often not NW versus NE in the abstract, but Panorama Hills/Coventry Hills versus NE townhome communities such as Saddle Ridge, Redstone, and Cornerstone. If your budget reaches the mid-$500,000s and you want detached, NE still offers materially more access than the strict NW district.
Before committing to any condo or condo-titled townhome, review reserve-fund documents, current fee levels, recent fee increases, and special-assessment risk. Alberta’s condo framework allows document fees and estoppel certificate fees, and Calgary buyers should treat condo governance as a financial due-diligence issue, not an administrative formality.
Finally, use real monthly carrying cost as the decision rule. Purchase price is only the opening number. A more expensive northern or NW-adjacent purchase may still be rational if it better fits your work pattern, future resale plan, and household stability, but the decision should be made after stress-test math, not before it.
Conclusions
For strict first-time affordability, Calgary NE is usually the better area. It offers lower benchmark prices across detached, row, and apartment categories, which lowers the cash needed for the down payment, reduces the insured mortgage balance, and makes stress-test qualification easier. For first-time buyers who can afford the premium and want stronger resale positioning, Calgary NW is often the better long-run choice, especially in detached housing. Panorama Hills and Coventry Hills sit between those poles and are often the most relevant “compromise” communities for buyers cross-shopping Calgary’s northern arc.